Here are some of the most frequently asked questions we get from customers about car finance. Whether you’re just getting started or need help understanding your agreement, we aim to give clear, honest, and straightforward answers. Our goal is to make car finance as simple.
Yes, you can apply for used Toyota finance through AutoMoney Trust.
Toyota offers a broad selection of vehicles on the used market, including compact cars such as the Aygo, family models such as the Corolla and Prius, and SUVs including the RAV4. This gives you a choice of different sizes and body styles depending on what you need from your next car.
Toyota is also well known for its hybrid vehicles, so the used market includes plenty of options for drivers interested in combining a petrol engine with electric assistance without relying solely on external charging.
You can explore your potential finance options before deciding on a particular Toyota, helping you to understand your budget before narrowing your search to an eligible vehicle.
Finance is subject to status, affordability checks and our lending and vehicle criteria. You can use the finance calculator to estimate example monthly repayments before applying.
The main difference is that with Hire Purchase (HP) you own the vehicle at the end of the agreement, whereas Personal Contract Purchase (PCP) includes an optional final balloon payment if you want to keep the car.
With Hire Purchase, you repay the full value of the vehicle through fixed monthly payments and become the owner once all payments and any option to purchase fee have been paid.
With PCP, monthly payments are usually lower because you are paying towards only part of the vehicle's value. At the end of the agreement, you can pay the balloon payment also known as a final payment) to keep the vehicle, return it, or choose another available option.
One of the main differences between HP and PCP finance is how ownership and mileage work. PCP agreements often include annual mileage limits and potential charges if the vehicle exceeds the agreed mileage or is returned with damage outside normal wear and tear. Hire purchase does not usually have mileage restrictions, making it a popular option for drivers who want flexibility and the certainty of owning the vehicle at the end of the agreement.
AutoMoney Trust offers hire purchase car finance only, providing customers buying used cars a straightforward agreement, fixed monthly payments, and the reassurance that they can own their vehicle once the agreement is completed.
Yes, an AutoMoney Trust hire purchase agreement includes a £199 admin fee as well as a £10 option to purchase fee, which is paid alongside your final monthly payment if you decide to keep the vehicle at the end of your agreement. This fee allows ownership of the car to transfer to you once all payments have been completed.
All applicable fees are clearly explained in your car finance agreement, so you can understand the costs involved before entering into a hire purchase agreement.
Additional charges may apply if payments are missed, including reminder letter fees or default interest. These charges are designed to cover the costs associated with managing missed payments and are detailed in our arrears fees and default interest schedule.
Unlike some finance providers, AutoMoney Trust does not charge early repayment fees if you choose to settle your agreement ahead of schedule. If you are considering paying off your car finance early, you can contact us to discuss your options and understand any settlement figure that may apply.
Yes, if you finance your car with AutoMoney Trust, you'll need to maintain fully comprehensive insurance for the entire duration of your hire purchase agreement. This is because the vehicle remains the property of AutoMoney Trust until you've made your final repayment and ownership transfers to you.
Comprehensive car insurance provides protection against a range of situations, including accidental damage, theft, fire and third-party claims. Keeping the vehicle insured for the full duration of your agreement helps protect both you and the lender by ensuring the car remains covered throughout the finance term.
When budgeting for a financed car, it is important to consider insurance as part of your overall running costs. Fully comprehensive cover is often more expensive than third party or third party fire and theft insurance, so make sure you include this alongside your monthly finance payments, fuel, servicing, and other vehicle expenses.
Some drivers also consider GAP insurance, which can help cover the difference between your insurer's settlement value if the vehicle is written off and the remaining balance on your car finance agreement when the outstanding balance may be higher than the vehicle's market value.
No, AutoMoney Trust does not charge early repayment fees on its hire purchase finance agreements, meaning you can complete your car finance settlement without paying additional penalty charges.
Whether you want to pay off your finance early, reduce your monthly commitments or sell your vehicle, settling your agreement ahead of schedule can provide greater financial flexibility and may reduce the overall cost of borrowing. To better understand how interest affects the total amount you repay, read our guide on what APR means in car finance.
If you're considering early settlement on car finance, you may be entitled to an interest rebate. Under the Consumer Credit Act 1974, customers who repay their hire purchase agreement early generally do not pay all of the interest that would have been charged over the remaining term. This reduces the total amount payable compared with continuing your monthly repayments until the end of the agreement.
If you would like to arrange a car finance settlement, you can request a settlement figure from AutoMoney Trust. This shows the total amount required to repay your finance agreement in full, taking into account any applicable interest rebate. Your settlement figure is valid for 28 days, giving you time to review the amount and decide whether early settlement is right for you.
Settlement policies can vary between lenders. While AutoMoney Trust does not charge early repayment fees, some providers may apply early settlement charges or calculate interest rebates differently. Before choosing to pay off your car finance early, always check the terms of your agreement and understand how your settlement amount has been calculated.
If you are considering a car finance settlement because you want to sell a financed car or part exchange your vehicle, our guide on Selling a Financed Car explains the process, what happens with outstanding finance, and the options available.
The best used Toyota depends on the journeys you make, the amount of space you need and whether you're interested in a conventional petrol car or a hybrid.
The Toyota Aygo is a compact option that may suit drivers who spend much of their time in towns and cities. The Yaris offers more everyday versatility while remaining relatively small, and hybrid versions are widely available on the used market.
For drivers who need more passenger and luggage space, the Toyota Corolla provides a more family-focused option and can be found in different body styles. Hybrid versions may appeal to drivers who want electric assistance without needing to plug the car to charge.
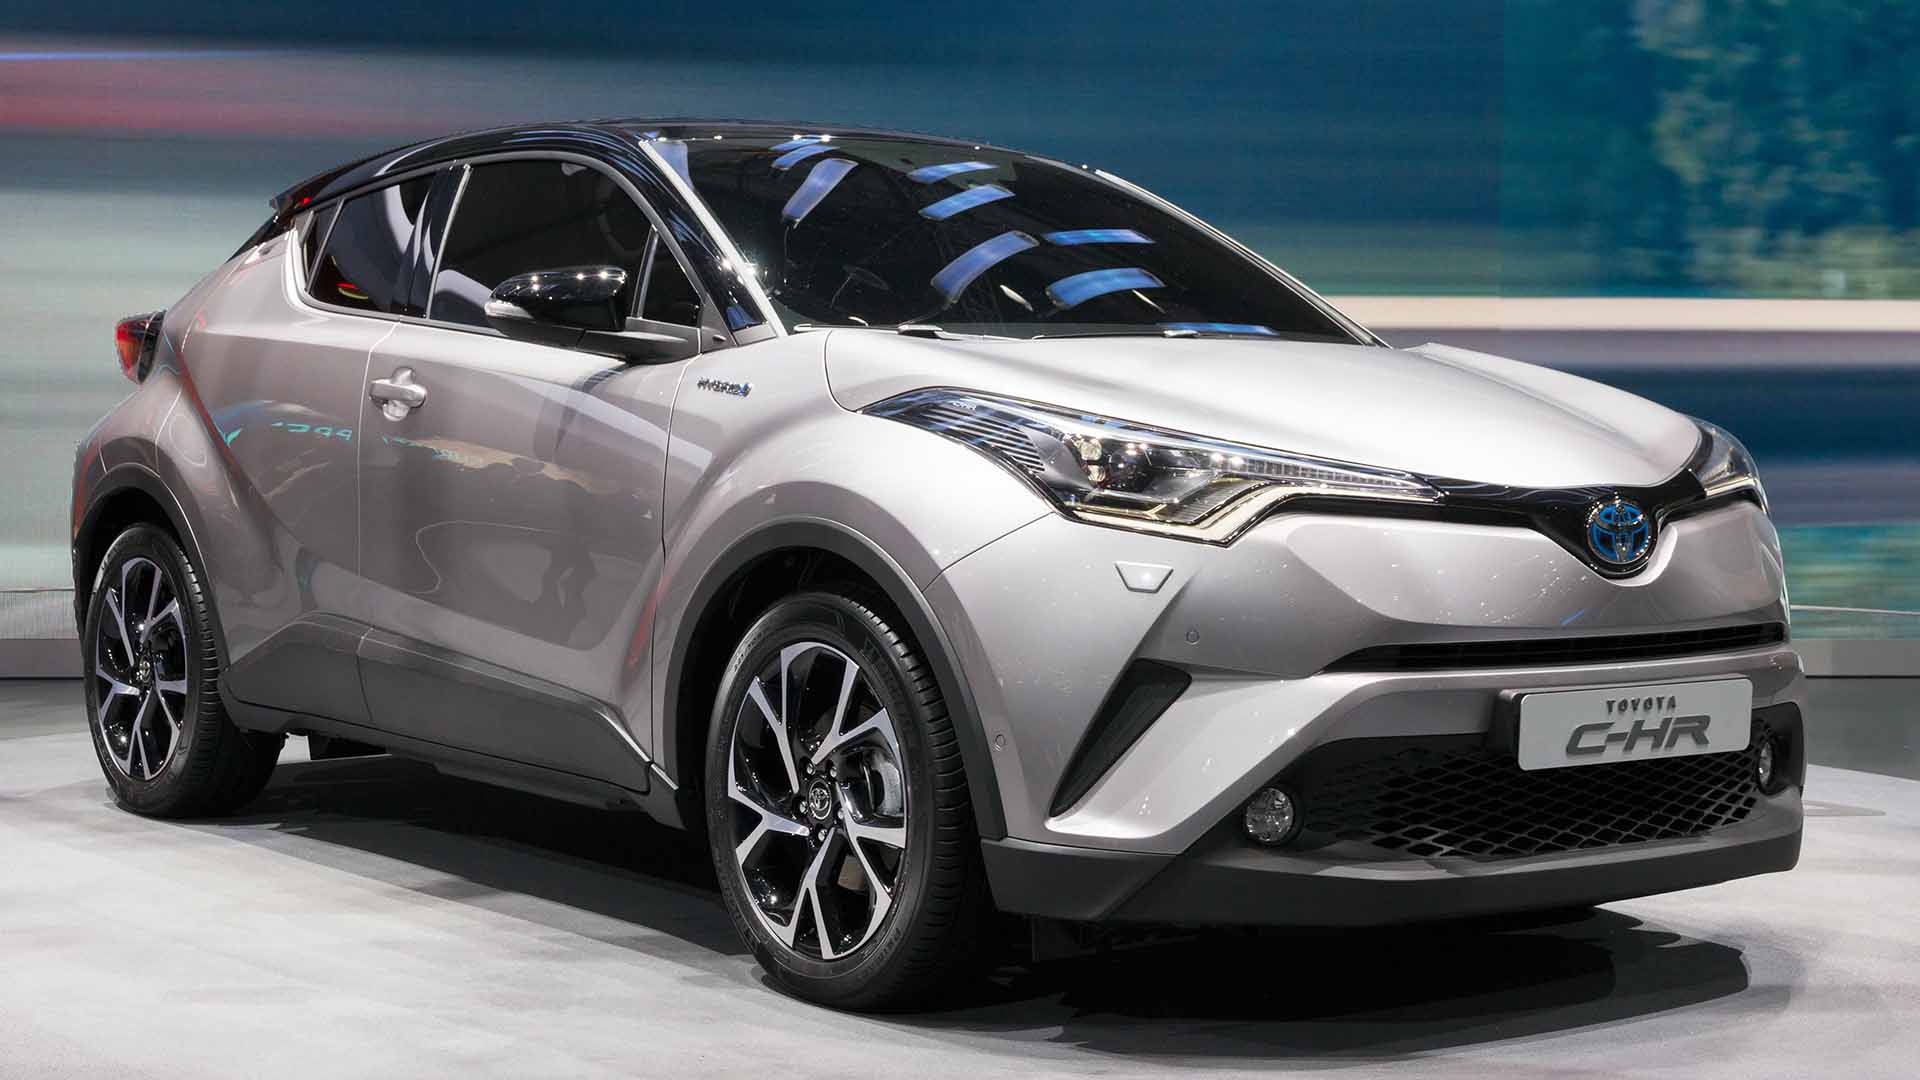
The Toyota C-HR takes a different approach, combining hybrid availability with distinctive crossover styling and a higher driving position. If space and SUV practicality are greater priorities, the Toyota RAV4 provides a larger alternative, with hybrid and plug-in versions available depending on age and specification.
The Toyota Prius is also worth considering if hybrid driving is your main priority, particularly if practicality and fuel efficiency matter more to you than SUV styling.
When comparing Toyota car finance, think about the types of journeys you make most often and whether you'll benefit from choosing a hybrid. This can help narrow the range before comparing individual used Toyotas within your budget.
The main difference is that with Hire Purchase (HP) you own the vehicle at the end of the agreement, whereas Personal Contract Purchase (PCP) includes an optional final balloon payment if you want to keep the car.
With Hire Purchase, you repay the full value of the vehicle through fixed monthly payments and become the owner once all payments and any option to purchase fee have been paid.
With PCP, monthly payments are usually lower because you are paying towards only part of the vehicle's value. At the end of the agreement, you can pay the balloon payment also known as a final payment) to keep the vehicle, return it, or choose another available option.
One of the main differences between HP and PCP finance is how ownership and mileage work. PCP agreements often include annual mileage limits and potential charges if the vehicle exceeds the agreed mileage or is returned with damage outside normal wear and tear. Hire purchase does not usually have mileage restrictions, making it a popular option for drivers who want flexibility and the certainty of owning the vehicle at the end of the agreement.
AutoMoney Trust offers hire purchase car finance only, providing customers buying used cars a straightforward agreement, fixed monthly payments, and the reassurance that they can own their vehicle once the agreement is completed.
Yes, an AutoMoney Trust hire purchase agreement includes a £199 admin fee as well as a £10 option to purchase fee, which is paid alongside your final monthly payment if you decide to keep the vehicle at the end of your agreement. This fee allows ownership of the car to transfer to you once all payments have been completed.
All applicable fees are clearly explained in your car finance agreement, so you can understand the costs involved before entering into a hire purchase agreement.
Additional charges may apply if payments are missed, including reminder letter fees or default interest. These charges are designed to cover the costs associated with managing missed payments and are detailed in our arrears fees and default interest schedule.
Unlike some finance providers, AutoMoney Trust does not charge early repayment fees if you choose to settle your agreement ahead of schedule. If you are considering paying off your car finance early, you can contact us to discuss your options and understand any settlement figure that may apply.
Yes, if you finance your car with AutoMoney Trust, you'll need to maintain fully comprehensive insurance for the entire duration of your hire purchase agreement. This is because the vehicle remains the property of AutoMoney Trust until you've made your final repayment and ownership transfers to you.
Comprehensive car insurance provides protection against a range of situations, including accidental damage, theft, fire and third-party claims. Keeping the vehicle insured for the full duration of your agreement helps protect both you and the lender by ensuring the car remains covered throughout the finance term.
When budgeting for a financed car, it is important to consider insurance as part of your overall running costs. Fully comprehensive cover is often more expensive than third party or third party fire and theft insurance, so make sure you include this alongside your monthly finance payments, fuel, servicing, and other vehicle expenses.
Some drivers also consider GAP insurance, which can help cover the difference between your insurer's settlement value if the vehicle is written off and the remaining balance on your car finance agreement when the outstanding balance may be higher than the vehicle's market value.
No, AutoMoney Trust does not charge early repayment fees on its hire purchase finance agreements, meaning you can complete your car finance settlement without paying additional penalty charges.
Whether you want to pay off your finance early, reduce your monthly commitments or sell your vehicle, settling your agreement ahead of schedule can provide greater financial flexibility and may reduce the overall cost of borrowing. To better understand how interest affects the total amount you repay, read our guide on what APR means in car finance.
If you're considering early settlement on car finance, you may be entitled to an interest rebate. Under the Consumer Credit Act 1974, customers who repay their hire purchase agreement early generally do not pay all of the interest that would have been charged over the remaining term. This reduces the total amount payable compared with continuing your monthly repayments until the end of the agreement.
If you would like to arrange a car finance settlement, you can request a settlement figure from AutoMoney Trust. This shows the total amount required to repay your finance agreement in full, taking into account any applicable interest rebate. Your settlement figure is valid for 28 days, giving you time to review the amount and decide whether early settlement is right for you.
Settlement policies can vary between lenders. While AutoMoney Trust does not charge early repayment fees, some providers may apply early settlement charges or calculate interest rebates differently. Before choosing to pay off your car finance early, always check the terms of your agreement and understand how your settlement amount has been calculated.
If you are considering a car finance settlement because you want to sell a financed car or part exchange your vehicle, our guide on Selling a Financed Car explains the process, what happens with outstanding finance, and the options available.
Many Toyotas can be relatively affordable to run, with the brand offering a wide range of petrol and hybrid vehicles. The actual cost will depend on the model, how it is driven and the condition of the individual car.
Toyota's self-charging hybrids, found in models such as the Yaris, Corolla, Prius, C-HR and RAV4, can completes part of a journey using electric power without needing to be plugged in. This can be particularly useful during slower, stop-start driving, where the hybrid-system can frequently switch between petrol and electric power.
Your driving pattern therefore matters. Someone regularly making urban and mixed journeys may experience different fuel consumption from a driver spending most of their time travelling at sustained motorway speeds.
It's also worth understanding which type of electrified Toyota you're financing. A conventional Toyota hybrid doesn't need external charging, whereas a plug-in hybrid version of models such as the RAV4 can be charged from an external power source and has different usage considerations.
Older hybrid Toyotas introduce another factor: the condition and remaining warranty cover of the hybrid battery. This doesn't automatically make an older hybrid expensive to own, but it's something to consider when comparing individual vehicles.
If you're considering Toyota car finance, look at how the particular powertrains fits your driving rather than assuming every hybrid will deliver the same running costs.
The main difference is that with Hire Purchase (HP) you own the vehicle at the end of the agreement, whereas Personal Contract Purchase (PCP) includes an optional final balloon payment if you want to keep the car.
With Hire Purchase, you repay the full value of the vehicle through fixed monthly payments and become the owner once all payments and any option to purchase fee have been paid.
With PCP, monthly payments are usually lower because you are paying towards only part of the vehicle's value. At the end of the agreement, you can pay the balloon payment also known as a final payment) to keep the vehicle, return it, or choose another available option.
One of the main differences between HP and PCP finance is how ownership and mileage work. PCP agreements often include annual mileage limits and potential charges if the vehicle exceeds the agreed mileage or is returned with damage outside normal wear and tear. Hire purchase does not usually have mileage restrictions, making it a popular option for drivers who want flexibility and the certainty of owning the vehicle at the end of the agreement.
AutoMoney Trust offers hire purchase car finance only, providing customers buying used cars a straightforward agreement, fixed monthly payments, and the reassurance that they can own their vehicle once the agreement is completed.
Yes, an AutoMoney Trust hire purchase agreement includes a £199 admin fee as well as a £10 option to purchase fee, which is paid alongside your final monthly payment if you decide to keep the vehicle at the end of your agreement. This fee allows ownership of the car to transfer to you once all payments have been completed.
All applicable fees are clearly explained in your car finance agreement, so you can understand the costs involved before entering into a hire purchase agreement.
Additional charges may apply if payments are missed, including reminder letter fees or default interest. These charges are designed to cover the costs associated with managing missed payments and are detailed in our arrears fees and default interest schedule.
Unlike some finance providers, AutoMoney Trust does not charge early repayment fees if you choose to settle your agreement ahead of schedule. If you are considering paying off your car finance early, you can contact us to discuss your options and understand any settlement figure that may apply.
Yes, if you finance your car with AutoMoney Trust, you'll need to maintain fully comprehensive insurance for the entire duration of your hire purchase agreement. This is because the vehicle remains the property of AutoMoney Trust until you've made your final repayment and ownership transfers to you.
Comprehensive car insurance provides protection against a range of situations, including accidental damage, theft, fire and third-party claims. Keeping the vehicle insured for the full duration of your agreement helps protect both you and the lender by ensuring the car remains covered throughout the finance term.
When budgeting for a financed car, it is important to consider insurance as part of your overall running costs. Fully comprehensive cover is often more expensive than third party or third party fire and theft insurance, so make sure you include this alongside your monthly finance payments, fuel, servicing, and other vehicle expenses.
Some drivers also consider GAP insurance, which can help cover the difference between your insurer's settlement value if the vehicle is written off and the remaining balance on your car finance agreement when the outstanding balance may be higher than the vehicle's market value.
No, AutoMoney Trust does not charge early repayment fees on its hire purchase finance agreements, meaning you can complete your car finance settlement without paying additional penalty charges.
Whether you want to pay off your finance early, reduce your monthly commitments or sell your vehicle, settling your agreement ahead of schedule can provide greater financial flexibility and may reduce the overall cost of borrowing. To better understand how interest affects the total amount you repay, read our guide on what APR means in car finance.
If you're considering early settlement on car finance, you may be entitled to an interest rebate. Under the Consumer Credit Act 1974, customers who repay their hire purchase agreement early generally do not pay all of the interest that would have been charged over the remaining term. This reduces the total amount payable compared with continuing your monthly repayments until the end of the agreement.
If you would like to arrange a car finance settlement, you can request a settlement figure from AutoMoney Trust. This shows the total amount required to repay your finance agreement in full, taking into account any applicable interest rebate. Your settlement figure is valid for 28 days, giving you time to review the amount and decide whether early settlement is right for you.
Settlement policies can vary between lenders. While AutoMoney Trust does not charge early repayment fees, some providers may apply early settlement charges or calculate interest rebates differently. Before choosing to pay off your car finance early, always check the terms of your agreement and understand how your settlement amount has been calculated.
If you are considering a car finance settlement because you want to sell a financed car or part exchange your vehicle, our guide on Selling a Financed Car explains the process, what happens with outstanding finance, and the options available.
Before financing a used Toyota, establish exactly which engine and powertrain you're buying, particularly if you're considering one of the brand's many hybrids models.
For a Yaris, Corolla, Prius, C-HR or RAV4 hybrid, look for evidence that the car has been maintained in line with the recommended schedule and find out what information is available about the hybrid battery's condition and any remaining warranty.
Don't assume all electrified Toyotas work in the same way. Most Toyota hybrids recharge their batteries while charging and don't need to be plugged in, whereas a plug-in hybrid has a larger battery that can be charged externally. If you're considering a plug-in model, check that the relevant charging equipment is included and that external charging will be practical for you .
It's also worth checking that the vehicle's specification matches the advert. Toyota models can be available in numerous trim levels and generations, so features such as cameras, driver-assistance technology, infotainment and parking equipment can differ between otherwise similar-looking cars.
Before applying for Toyota car finance, make sure you're satisfied with the individual car's maintenance history, hybrid system and specification rather than choosing it solely because of Toyota's wider reputation for reliability.
The main difference is that with Hire Purchase (HP) you own the vehicle at the end of the agreement, whereas Personal Contract Purchase (PCP) includes an optional final balloon payment if you want to keep the car.
With Hire Purchase, you repay the full value of the vehicle through fixed monthly payments and become the owner once all payments and any option to purchase fee have been paid.
With PCP, monthly payments are usually lower because you are paying towards only part of the vehicle's value. At the end of the agreement, you can pay the balloon payment also known as a final payment) to keep the vehicle, return it, or choose another available option.
One of the main differences between HP and PCP finance is how ownership and mileage work. PCP agreements often include annual mileage limits and potential charges if the vehicle exceeds the agreed mileage or is returned with damage outside normal wear and tear. Hire purchase does not usually have mileage restrictions, making it a popular option for drivers who want flexibility and the certainty of owning the vehicle at the end of the agreement.
AutoMoney Trust offers hire purchase car finance only, providing customers buying used cars a straightforward agreement, fixed monthly payments, and the reassurance that they can own their vehicle once the agreement is completed.
Yes, an AutoMoney Trust hire purchase agreement includes a £199 admin fee as well as a £10 option to purchase fee, which is paid alongside your final monthly payment if you decide to keep the vehicle at the end of your agreement. This fee allows ownership of the car to transfer to you once all payments have been completed.
All applicable fees are clearly explained in your car finance agreement, so you can understand the costs involved before entering into a hire purchase agreement.
Additional charges may apply if payments are missed, including reminder letter fees or default interest. These charges are designed to cover the costs associated with managing missed payments and are detailed in our arrears fees and default interest schedule.
Unlike some finance providers, AutoMoney Trust does not charge early repayment fees if you choose to settle your agreement ahead of schedule. If you are considering paying off your car finance early, you can contact us to discuss your options and understand any settlement figure that may apply.
Yes, if you finance your car with AutoMoney Trust, you'll need to maintain fully comprehensive insurance for the entire duration of your hire purchase agreement. This is because the vehicle remains the property of AutoMoney Trust until you've made your final repayment and ownership transfers to you.
Comprehensive car insurance provides protection against a range of situations, including accidental damage, theft, fire and third-party claims. Keeping the vehicle insured for the full duration of your agreement helps protect both you and the lender by ensuring the car remains covered throughout the finance term.
When budgeting for a financed car, it is important to consider insurance as part of your overall running costs. Fully comprehensive cover is often more expensive than third party or third party fire and theft insurance, so make sure you include this alongside your monthly finance payments, fuel, servicing, and other vehicle expenses.
Some drivers also consider GAP insurance, which can help cover the difference between your insurer's settlement value if the vehicle is written off and the remaining balance on your car finance agreement when the outstanding balance may be higher than the vehicle's market value.
No, AutoMoney Trust does not charge early repayment fees on its hire purchase finance agreements, meaning you can complete your car finance settlement without paying additional penalty charges.
Whether you want to pay off your finance early, reduce your monthly commitments or sell your vehicle, settling your agreement ahead of schedule can provide greater financial flexibility and may reduce the overall cost of borrowing. To better understand how interest affects the total amount you repay, read our guide on what APR means in car finance.
If you're considering early settlement on car finance, you may be entitled to an interest rebate. Under the Consumer Credit Act 1974, customers who repay their hire purchase agreement early generally do not pay all of the interest that would have been charged over the remaining term. This reduces the total amount payable compared with continuing your monthly repayments until the end of the agreement.
If you would like to arrange a car finance settlement, you can request a settlement figure from AutoMoney Trust. This shows the total amount required to repay your finance agreement in full, taking into account any applicable interest rebate. Your settlement figure is valid for 28 days, giving you time to review the amount and decide whether early settlement is right for you.
Settlement policies can vary between lenders. While AutoMoney Trust does not charge early repayment fees, some providers may apply early settlement charges or calculate interest rebates differently. Before choosing to pay off your car finance early, always check the terms of your agreement and understand how your settlement amount has been calculated.
If you are considering a car finance settlement because you want to sell a financed car or part exchange your vehicle, our guide on Selling a Financed Car explains the process, what happens with outstanding finance, and the options available.